Brownfield land is the least contested ground in the planning system, and the most commonly misunderstood. Most of the mistakes are definitional – people call land brownfield when national policy does not – and the rest are financial, because the reliefs come with conditions nobody reads until the claim fails.
These ten facts are drawn from the National Planning Policy Framework published on 17 August 2026 and current tax and permitted development rules. They are the ones that change what a site is worth.
1. “Brownfield” has a legal definition, and it is narrower than you think
The Framework treats brownfield land as previously developed land: land lawfully developed and occupied, now or formerly, by a permanent structure and its fixed surface infrastructure, including the curtilage. It expressly excludes land last occupied by agricultural or forestry buildings, land where restoration was secured through development management (minerals, landfill, renewables), residential gardens, parks, recreation grounds and allotments, and land where the remains of the structure have blended into the landscape.
Read that list again if you source rurally. A disused farmyard is not previously developed land in policy terms, however industrial it looks.
2. Development within a settlement now starts from yes
Policy S4 of the 2026 Framework says development proposals within settlements should be approved unless the benefits would be substantially outweighed by adverse effects, assessed against the Framework’s national decision-making policies. Most brownfield land is inside a settlement boundary, which is where that policy does its work.
Which makes the boundary itself the thing to check first – how planners decide what is inside a settlement is the companion question.
3. Remediating bad ground earns substantial weight
Policy L2 says substantial weight should be given to the benefits where a proposal remediates despoiled, degraded, derelict, contaminated or unstable land, or brings vacant and underused land and buildings back into use. Contamination is a cost, but in the planning balance it is also an argument. Say so in the planning statement; a surprising number of applications do not.
4. Land Remediation Relief is real money, with real conditions
Land Remediation Relief is a Corporation Tax relief under Part 14 of the Corporation Tax Act 2009. It gives an extra 50% deduction on eligible revenue expenditure on top of the normal 100%, and a 150% deduction on eligible capital expenditure. A loss-making company can surrender losses for a 16% cash tax credit.
The conditions catch most people out:
- It is for companies. There is no equivalent for an individual or a partnership of individuals.
- For the derelict land limb, the land must have been continuously derelict since 1 April 1998.
- Contamination must be present as a result of industrial activity.
- The polluter cannot claim. If your company, or another party with an interest in the land, caused the contamination or dereliction, the relief is not available.
- Subsidised expenditure does not qualify, and capital expenditure eligible for capital allowances is excluded.
Treat the rules as live. The government concluded in 2026 that the relief is not fully achieving its objective and consulted on reform, with responses closing on 21 September 2026. If you are modelling a claim into an appraisal for a scheme completing in 2028, check where that landed.
5. It is a reduced VAT rate on conversions, not an exemption
Converting a non-residential building into dwellings is generally subject to the 5% reduced rate of VAT on the qualifying construction services, under section 7 of VAT Notice 708. Renovating a dwelling that has been empty for at least two years can also qualify at 5%, under section 8. A relevant housing association converting a non-residential building can reach the zero rate.
Five percent rather than twenty on the build cost of a conversion is material to a residual land value. It is also easy to lose by getting the contract structure wrong, so take advice before the works start rather than at the VAT return.
6. Class MA is the fastest route on a commercial building – if it qualifies
Class MA of the General Permitted Development Order allows change of use from Class E (commercial, business and service, which includes shops, offices and light industrial) to Class C3 dwellinghouses, subject to prior approval rather than full planning permission. There is no floorspace cap, and the building must have been in a qualifying use for a continuous period of at least two years before the prior approval application.
It does not apply to listed buildings or their curtilage, scheduled monuments, sites of special scientific interest, National Parks, the Broads, National Landscapes or World Heritage Sites. Prior approval covers transport, contamination, flooding, noise from commercial premises, natural light, impacts on industrial and storage areas, loss of nurseries and health centres, and fire safety. And an Article 4 direction can remove the right entirely, which is exactly what many town centre authorities have done.
The detail is worth reading properly – the Class MA guide covers the tests one at a time.
7. Agricultural buildings are a different route entirely
Because farm buildings are excluded from previously developed land, the rural conversion play is not a brownfield play. It is Class Q, which has its own thresholds and its own refusals. Do not argue a barn as brownfield; argue it as Class Q.
8. Brownfield land registers are statutory, and can carry permission in principle
Every local planning authority in England must prepare and maintain a register of previously developed land, kept in two parts, under the Town and Country Planning (Brownfield Land Register) Regulations 2017. The Framework’s glossary is explicit about why that matters: where authorities follow the required procedures, they can trigger a grant of permission in principle for residential development on suitable sites in their registers.
These registers are published. They are a free list of sites the council has already assessed as appropriate for housing, and they are underread.
9. Existing infrastructure is an advantage you have to verify
A brownfield site usually comes with a road, a connection and a drainage outfall, which is genuinely worth money against a greenfield site that needs all three. But capacity is not the same as presence. Check the sewer capacity, the electricity connection quote and the highway adoption status before you price any of it as a saving – a connection offer with a reinforcement charge on it can be the single largest abnormal in the appraisal.
10. The Green Belt rules are different, and they are the ones that moved
Previously developed land in the Green Belt has its own policy, and the 2026 Framework keeps the grey belt concept alongside it. If your brownfield site is washed over by Green Belt, the question is not the settlement policy above – it is which Green Belt exception you are relying on, and whether the Golden Rules on affordable housing apply to your scheme.
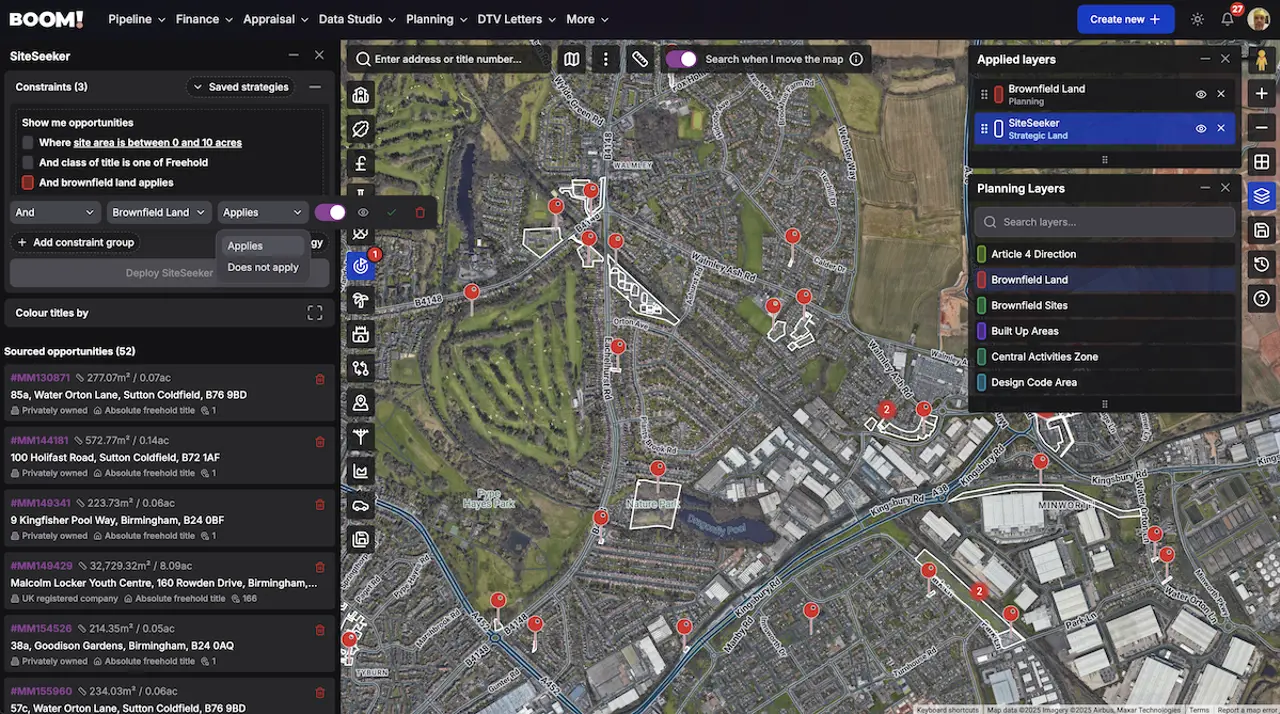
Finding the sites this applies to
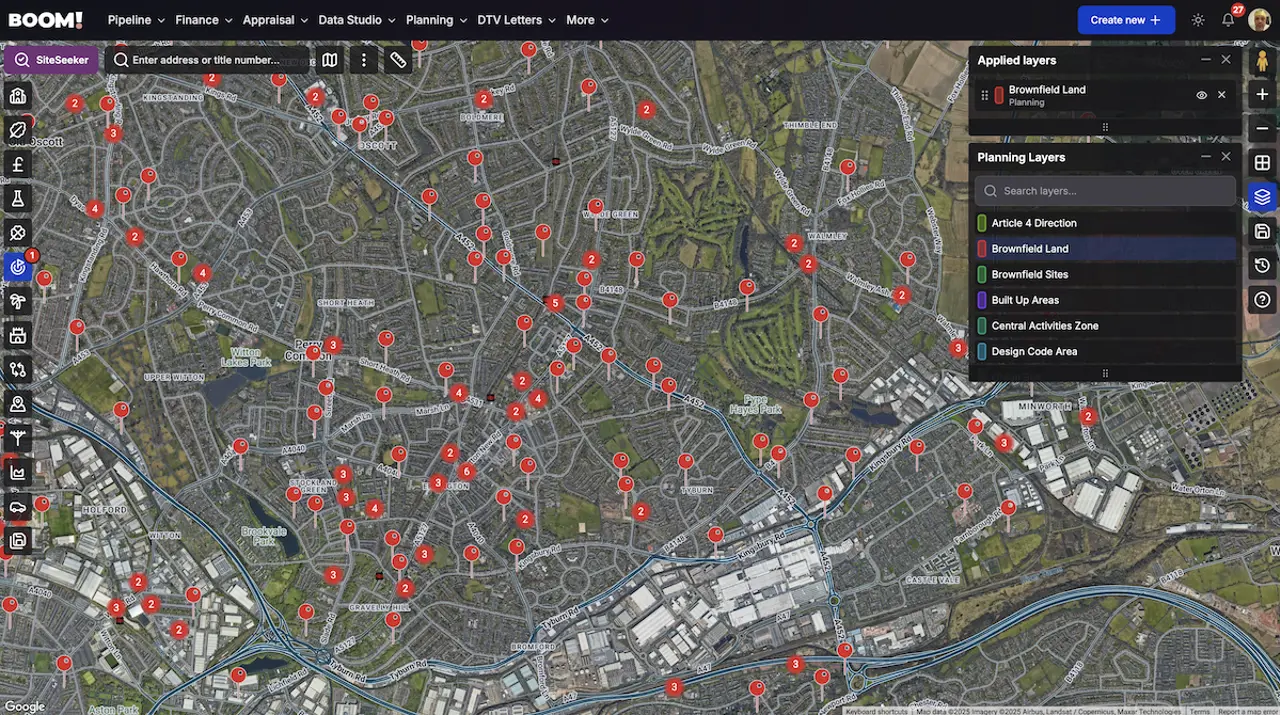
BOOM! carries brownfield land as a map layer in Data Studio, so you can see which parcels are on the register without opening a council GIS one authority at a time. In SiteSeeker you can filter brownfield land in or out of a search, and layer it with the planning applications history to see what has already been tried on a site and what was refused.